[비즈한국] The possibility of a US initial public offering (IPO) for Solidigm, a company launched based on the Intel NAND and SSD business that SK Hynix agreed to acquire for approximately $9 billion in 2020, is being discussed. There are even forecasts suggesting a company valuation of up to $150 billion, with the potential to raise about $15 billion through the IPO.
Reuters reported on September 25, citing multiple sources, that Solidigm is considering a US IPO as early as 2027. According to the report, Solidigm has conducted a "bake-off," a process where companies invite investment banks to compete for the role of lead underwriter for the IPO. Projections suggest that the company could raise roughly $15 billion and reach a valuation of up to $150 billion. However, Reuters noted that the deal's scale and timing could change depending on market conditions and that nothing has been finalized.
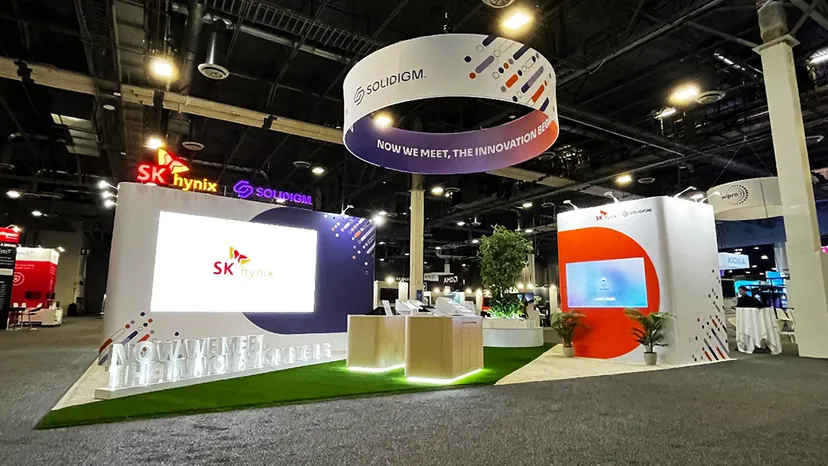
It is difficult to compare the $9 billion and $150 billion figures simply as "acquisition price versus current valuation." The $9 billion was the amount SK Hynix agreed to pay in 2020 to acquire Intel’s NAND SSD business, NAND components and wafer business, and the Dalian production facility in China. In contrast, $150 billion is the potential valuation currently discussed in the context of an IPO for Solidigm, which has since undergone business restructuring, additional investment, and an expansion of its enterprise SSD (eSSD) business for AI data centers.
SK Hynix also issued an official statement on the 1st as rumors of the listing spread. The company stated, "Nothing has been finalized regarding Solidigm," adding, "We must evaluate not only the form of capital—whether external or internal—but also the overall economic impact on existing shareholders." This implies that the company intends to prioritize long-term corporate and shareholder value. This stance suggests that a Solidigm IPO is currently being considered as one of many capital-raising options rather than a confirmed management plan.
SK Hynix Has 88 Trillion Won in Cash Equivalents… Considering Both Internal and External Funds
SK Hynix has sufficient financial capacity. At the end of the second quarter of this year, SK Hynix's cash and cash equivalents stood at 88 trillion won, an increase of 33.6 trillion won from the previous quarter. Total debt decreased to 18.6 trillion won, and net cash expanded to 69.4 trillion won. Therefore, it is difficult to view the company’s financial situation as one that necessitates external funding for Solidigm investments. In fact, SK Hynix stated that it is considering both internal and external funds as options.
In its official statement, the company explained that even with sufficient financial capacity, using internal funds for all investments is not necessarily the best approach. The goal is to balance the investment needs to strengthen Solidigm's competitiveness with the overall capital allocation efficiency of the group.
It is true that the need for investment in Solidigm is growing. Solidigm is expanding its high-capacity eSSD business for AI data centers. Its flagship product, the D5-P5336, offers a capacity of up to 122.88TB. This is double the capacity of the previous 61.44TB product, designed specifically for AI and large-scale data processing storage devices.
SK Hynix also reorganized its Solidigm business in January this year while creating a new US AI business organization. The existing legal entity, SK Hynix NAND Product Solutions Corp., was converted into a company responsible for AI business, while the NAND SSD-related business was transferred to the newly established Solidigm Inc. At the time, SK Hynix announced plans to invest up to $10 billion in its US AI business organization.
Solidigm 96.86% Stake… Potential for Dilution Depends on Listing Structure
According to SK Hynix's consolidated financial statements at the end of June this year, Solidigm Inc. is classified as a consolidated subsidiary, with a disclosed stake of 96.86%. SK Hynix NAND Product Solutions Corp., which controls the Solidigm business, is also a consolidated subsidiary of SK Hynix.
It is currently unknown how SK Hynix's stake might change even if an IPO occurs. If Solidigm issues new shares to raise capital, the existing stake could be diluted. Conversely, the outcome would vary depending on the combination of methods, such as the proportion of secondary shares sold versus other capital-raising techniques.
The $15 billion fundraising figure reported by Reuters refers to a potential scale of new share issuance and is not a finalized number. Therefore, it is difficult to calculate SK Hynix's post-IPO stake at this stage. Aware of this, SK Hynix stated it would comprehensively review the economic effects on existing shareholders rather than focusing solely on the capital-raising method.
The starting point for Solidigm was Intel's NAND business. In October 2020, SK Hynix signed an agreement to acquire Intel's NAND memory and storage business for $9 billion. The deal included the NAND SSD business, NAND component and wafer business, and the Dalian NAND production facility. Intel’s Optane business was excluded from the transaction. The contract at the time was structured to be completed in two phases.
SK Hynix launched Solidigm (legal name SK Hynix NAND Product Solutions Corp.) after completing the first phase of the transaction in 2021. Although it faced difficulties due to the NAND market downturn, it has recently reorganized its business focusing on high-capacity eSSDs for AI data centers. SK Hynix explained in its official statement that Solidigm is currently strengthening its business competitiveness with a focus on high-capacity eSSDs for AI data centers.
The market environment has also changed. With the spread of generative AI, the demand for high-capacity SSDs is increasing as data centers see a rapid rise in both computational volume and the scale of data that needs to be stored. Solidigm is supplying high-capacity QLC SSDs, including the 122.88TB product, targeting AI and data-intensive workloads.
The possibility of investment in a US production facility for Solidigm has also been raised. Reuters reported last month that Solidigm is considering building a NAND flash production plant in upstate New York. However, discussions are in the early stages, and neither the investment nor its scale has been decided.
Minority Shareholders Concerned About "Shareholder Value Damage"… Controversy Over Double Listing
As the possibility of a Solidigm IPO became known, a controversy over "double listing" emerged in South Korea. The minority shareholder platform Act argued on the 2nd that the Solidigm listing plan should be reconsidered. Act claims that if Solidigm receives external investment through methods like new share issuance, the economic value enjoyed by existing SK Hynix shareholders could be diluted. They have also mentioned the possibility of submitting a petition to the Korea Exchange.
However, it is difficult to equate the Solidigm listing to the typical "listing of a subsidiary after a physical spin-off" that has caused controversy domestically. Solidigm was not created by physically spinning off an existing SK Hynix business division; rather, it was launched after acquiring the NAND/SSD business from an external company, Intel. Its business structure was further adjusted this year during the reorganization of the US AI business.
On the other hand, there is room for debate in that the economic interests of the parent company's shareholders could change if a separate entity raises capital from external investors and goes public. Some argue that shareholder value could actually increase if Solidigm grows through external investment. SK Hynix, mindful of this, stated, "We must evaluate the overall economic impact on existing shareholders rather than focusing on the form of the transaction, such as whether it constitutes a double listing."