

[BizHanKook] SK Hynix has officially dropped its plan to list its U.S. sub-subsidiary, Solidigm, on the Nasdaq. With the cancellation of an external fundraising scheme that was estimated to reach up to 20 trillion won, the company now faces the challenge of securing new funding for projects such as new production facilities in the U.S. Amid intensifying competition in the memory industry driven by the expansion of AI data centers, the market is turning its attention to the upcoming Q3 earnings announcement, where the company is expected to reveal additional shareholder return plans and its future capital allocation strategy.
Intended to Fund New York Facilities, But...
In a regulatory filing on the 23rd, SK Hynix announced that it would suspend the review of both pre-IPO investment and an initial public offering (IPO) for Solidigm. This comes 79 days after the news of IPO preparations first surfaced on August 5. The company explained that given the increased financial market volatility and the correction in semiconductor stocks, it was necessary to re-evaluate whether an IPO at this time was the most favorable choice for existing shareholders. This does not mean that Solidigm’s growth potential or investment needs have changed.
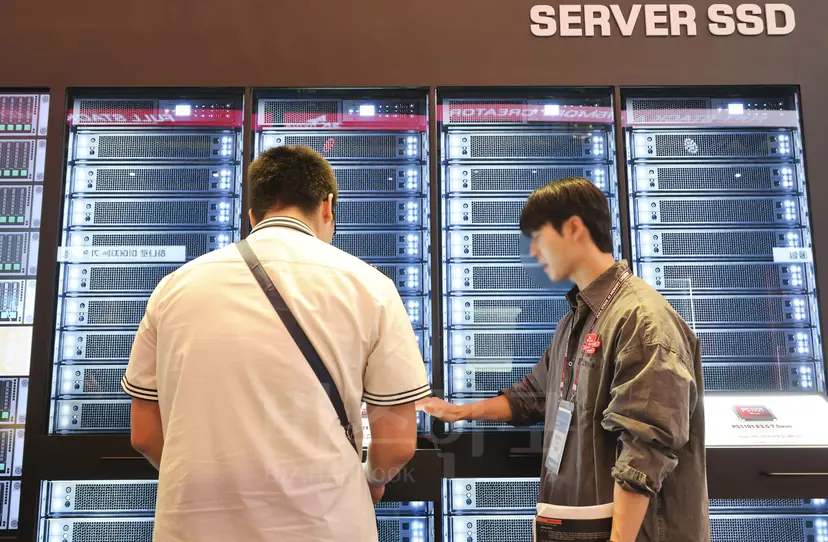
Solidigm was established in 2021 after SK Hynix acquired Intel’s NAND and SSD business for approximately $9 billion (about 11 trillion won). Its flagship product is the enterprise solid-state drive (eSSD). An SSD is a device that stores data on semiconductor memory. eSSDs are used in data centers and corporate servers to reliably store and process large-scale data, and demand is growing alongside the increase in data required for AI training and inference.
Market forecasts previously suggested that Solidigm’s corporate value could reach $100 billion to $150 billion (130 trillion to 200 trillion won), with IPO proceeds potentially hitting $10 billion to $15 billion (13 trillion to 20 trillion won). It was observed that these funds were intended for new production facilities in New York, separate from the capacity expansion at the Dalian plant in China.
‘5-Tier Ownership’ and ‘Double Listing’ Controversy, Overseas IPOs Also Under Regulatory Scrutiny
While SK Hynix cited market conditions as the reason for the suspension, the industry views the double listing controversy as the definitive cause. The semiconductor ownership structure of SK Group flows from SK Inc. to SK Square, SK Hynix, AI Company, and finally Solidigm. Concerns were raised that if Solidigm issued new shares to attract external capital, SK Hynix's indirect stake would be diluted, potentially reducing the share of future profits for existing shareholders.
With the double listing guidelines implemented in August now applying to overseas listings, and with Financial Supervisory Service Governor Lee Chan-jin and Financial Services Commission Chairman Lee Eok-won repeatedly identifying Solidigm as a target for regulation during the parliamentary audit, the burden of pursuing the listing grew. Observers note that this case may also affect the schedules of other subsidiaries preparing for overseas listings, such as Hyundai Motor Group's Boston Dynamics.
The problem is that the need for capacity expansion remains. Alternatives such as direct capital injection, borrowing, or third-party paid-in capital increases are being discussed, but each comes with the burden of cash pressure, interest costs, or equity dilution. As of the end of the second quarter, SK Hynix held 88 trillion won in cash equivalents and 18.6 trillion won in debt. However, since the company has since completed a share buyback program of approximately 40 trillion won, it is difficult to consider that cash balance as currently available capital. Additionally, with domestic investments such as the Cheongju M15X and the Yongin Semiconductor Cluster running in parallel, the company must carefully assess how much capital can be allocated to Solidigm.
While direct investment or borrowing by SK Hynix are considered alternative funding methods, a specific strategy has not yet been decided. With fewer opportunities to attract external capital, the challenge lies in how to balance the resources needed for Solidigm's investment, domestic facility projects, and shareholder returns.
Stock Price Rebounds… Focus Shifts to Shareholder Return Announcement
On the day of the announcement to stop the IPO review, SK Hynix's stock price closed at 1,277,000 won, up 4.42%. However, compared to the closing price on September 23, it is down about 31.4% over the past month.
Yang Hyun-kyung, a researcher at iM Securities, noted, "The withdrawal of Solidigm's U.S. listing is a factor that can alleviate concerns over discounts due to double listing and equity dilution," adding, "However, as opportunities for external capital raising decrease, the burden of future investment costs may increase."
The key event is the earnings announcement on the 28th. According to FnGuide, the consensus for SK Hynix's third-quarter operating profit is 76.964 trillion won, which would be a record high. Regarding rumors of a 16 trillion won special dividend utilizing the proceeds from the sale of Kioxia shares, SK Hynix stated that "nothing has been decided" and that it would reveal additional return policies during the earnings release.
As the scale of returns increases, the balance with investment resources becomes critical. How the company prioritizes multi-trillion won facility investments versus shareholder returns will be a key variable influencing the stock price. Kim Sun-woo, a researcher at Meritz Securities, predicted, "I interpret this as the company declaring that enhancing shareholder value is its top priority over its envisioned growth strategy," and added, "More effective and concrete shareholder value enhancement measures will likely be presented at the earnings announcement."