[BizHanKook] When Samsung Electronics’ stock price was in the 120,000 won range, I asked an expert whether it was a good time to buy. The reply was essentially, “I thought 100,000 won was expensive, so how could 120,000 won be any better?” While I hesitated to buy, the stock price kept rising, and I eventually bought it in the 220,000 won range earlier this year. Since then, the price surged to the 370,000 won range during intraday trading, only to recently slide back to the 220,000 won level.
My feelings about the same price are complex. When I recall the 120,000 won mark, it feels expensive, but when I remember the 370,000 won mark, it feels cheap. However, neither is a sufficient basis for explaining its current value. Regardless of the price I paid or how high the stock went, the company’s future earnings remain unchanged. Whether 220,000 won is cheap or expensive should be judged based on current profit projections.
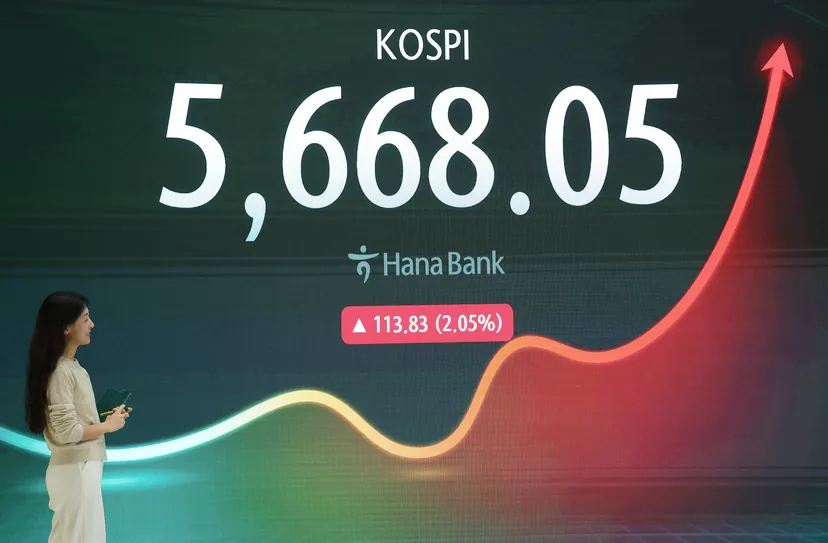
At the end of last week, the New York stock market revealed its anxiety about "future earnings." On October 30, local time, Intel’s stock price fell by 28.58%, the Nasdaq index by 2.86%, and the Philadelphia Semiconductor Index by 7.20%. Following the earnings reports of Intel and Amazon, concerns grew over whether massive AI investments could actually translate into sufficient profits. This is not just someone else's problem for domestic semiconductor investors.
It is difficult to interpret this shock solely as a concern that AI demand has evaporated. While Intel predicted that the slump in the PC market would continue until the first half of next year, it also explained that demand for server CPUs remains strong. Production setbacks caused by factory accidents also weighed on earnings projections. Intel’s stock price decline is a mix of varying demand by business sector, production issues, and heightened market expectations. It is difficult to conclude that Samsung Electronics’ performance will also deteriorate based on Intel’s slump.
Nevertheless, the question posed by this sell-off is how quickly companies using AI can recoup their investments. Expenditures by companies building data centers become revenue for semiconductor suppliers. However, orders only continue if the buyer can keep absorbing those costs. The AI investment that increased Samsung Electronics’ revenue is a significant expenditure for its clients. If clients slow down their investment speed, it could also affect Samsung Electronics’ orders.
The rise in memory prices illustrates this connection well. While it leads to expectations of higher selling prices and profits for Samsung Electronics, it is a cost burden for companies that buy memory to build PCs and servers. Intel explained that high memory costs are putting pressure on the PC market. This suggests that while price increases boost the supplier's profits, they can weaken the purchasing power of the final consumer. Of course, there is insufficient evidence yet to interpret the burden seen in the PC market as an overall contraction in AI server demand.
Samsung Electronics' actual performance has improved significantly. The operating profit for the fourth quarter of last year, which could be verified at the time of purchase, was 20.1 trillion won. In the third quarter of this year, it reached 107.4 trillion won, more than a fivefold increase. The company explained its expanded sales of HBM4 and server memory, and predicted that the industry upturn would continue next year due to AI investment and supply constraints. Even at the same 220,000 won, the scale of profit being generated has changed compared to before.
What investors are pricing now is the duration of these high profits. In businesses like semiconductors, where profitability fluctuates significantly based on market conditions, it is easy to mistake a year of high profits for performance that will repeat over a long period. When profits surge during a boom, the price-to-earnings ratio (PER) also drops. However, if profits decrease later, the PER rises even if the stock price remains the same. The price burden calculated based on recent strong earnings can be different from the burden once the boom weakens.
This decline should be viewed as a reassessment of the speed of return on investment rather than the end of the AI industry. Even if the AI business grows, if it fails to generate profits as quickly and substantially as investors expected, the valuation multiples of the stock may decline. The issue at hand is the gap between the growth expectations that supported the stock price and the speed at which actual money is being earned. This gap cannot be bridged by the mere belief that it is a good industry.
When looking at Samsung Electronics, one must watch whether memory is selling well and whether clients can continue their AI investments. If orders are maintained, a stock price decline can be considered a buying opportunity. However, if clients cut investments and delay orders, Samsung Electronics' profit outlook will change. In such a case, continuing to buy on the way down because the price has fallen could lead to even greater losses.
The questions to ask experts must also change. It is difficult to gain a basis for judgment just by asking, "Should I buy now?" One should ask what earnings were expected to calculate a fair price, and how much that price would drop if the client's investment plans were to change.
Samsung Electronics is back in the 220,000 won range. I do not believe the growth story is over just because of this decline. Nor can I say it will unconditionally recover just because it once rose to 370,000 won. The standard for evaluating the current price is the sustainability of current profits. Rather than vague optimism or fear, a calm assessment of the money clients are spending and the money Samsung Electronics is earning is the necessary attitude amidst concerns over AI investments.