

[비즈한국] As the number of overseas consumers seeking second-hand domestic items, such as K-pop photo cards and limited-edition goods, continues to rise, the second-hand market is expanding beyond national borders. While the second-hand trade has evolved from simple person-to-person exchanges into a professional "re-commerce" industry that even encompasses export markets, critics point out that the relevant tax policies remain stuck in the past. In particular, discussions have begun regarding whether the current system—which only allows businesses purchasing items from individuals to claim value-added tax (VAT) deductions on specific items like used cars and recycled waste—is compatible with the changing market environment.
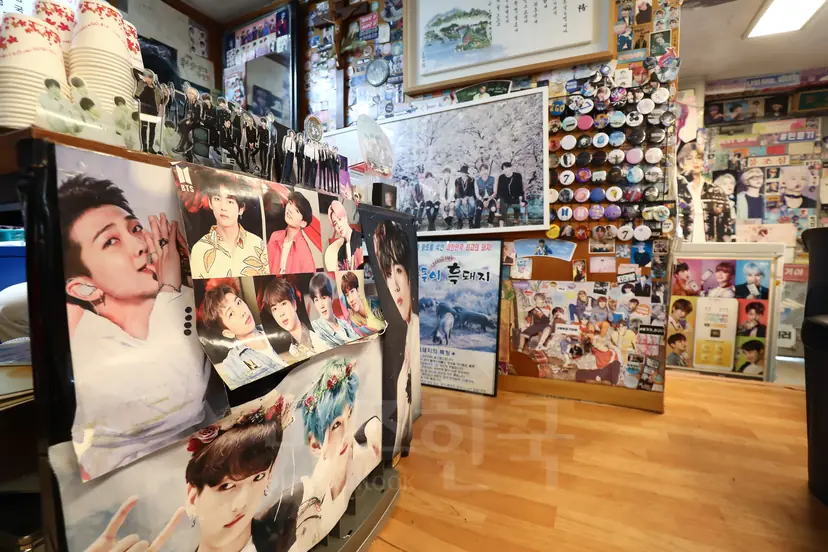
According to the Korea Internet & Security Agency, the domestic second-hand market is estimated to have grown about 10-fold, from 4 trillion won in 2008 to 43 trillion won in 2025. The global re-commerce market is also projected to reach $2.87 trillion (approximately 4,216 trillion won) by 2035. The overseas trade of domestic second-hand goods is also increasing rapidly. According to Bungaejangteo, the number of transactions on "Bunjang Global"—a service that allows overseas users to purchase items from Korean sellers—increased by 56% in the first half of this year compared to the same period last year.
As overseas fans purchase items once owned by domestic fans, the distribution scope of second-hand goods has widened. In particular, as items once circulated within Korea, such as K-pop photo cards and limited-edition goods, find new demand overseas, second-hand goods are emerging as a form of export product. Second-hand trade is also being evaluated as a pillar of the circular economy, as it extends the lifespan of products by selling them to other consumers instead of discarding them after one use.
Individuals sell, businesses handle overseas shipping… Tax burdens arise when buying second-hand goods directly
Overseas trade of domestic second-hand goods is conducted through second-hand platforms and purchase/delivery agencies. When a domestic individual seller lists an item on a platform, an overseas consumer purchases it, and the seller sends the item to a domestic delivery agency's warehouse. The agency then verifies the item and processes international shipping and customs clearance. This structure allows domestic second-hand goods to reach overseas consumers without the individual seller needing to handle international shipping themselves.
The market for businesses that professionally distribute second-hand goods—by purchasing them directly from individuals and reselling them to domestic and foreign consumers—is also growing. The issue is that the VAT treatment in this case differs from standard distribution. Typically, in business-to-business transactions, the seller issues a tax invoice, and the purchasing business uses it to deduct input tax. However, when purchasing second-hand goods from non-business individuals, it is difficult to apply this method because a tax invoice cannot be obtained.
To compensate for this, Article 108 of the current Restriction of Special Taxation Act allows businesses that purchase recycled waste or used cars to claim a "deemed input tax deduction" based on certain requirements. This system treats a portion of the acquisition cost as having input tax, even if a formal tax invoice is not received. The deduction rate is 10/110 of the acquisition cost for used cars and 3/103 for recycled waste.
However, most second-hand goods, such as used clothing, photo cards, and general electronic devices, are excluded from this. Even if the business of buying goods from individuals for resale is the same, VAT deductibility depends on the type of item handled. This is why critics argue that, given the significant expansion in transaction items and market scale compared to the past when the second-hand market centered on used cars, it is necessary to examine whether maintaining the current scope of deduction is appropriate.
Used cars qualify, but photo cards don't?
The problem becomes even more complex with exports. Under the current VAT Act, exports of goods are in principle subject to a 0% zero-tax rate. General exporters can deduct or receive a refund for the VAT paid when purchasing goods within Korea as input tax. On the other hand, businesses that purchase second-hand goods from individuals struggle to deduct their purchase costs in the same way because they lack tax invoices.
The industry believes there is a lack of equity between the export of new products and the export of second-hand goods. Even when selling products to overseas consumers, the tax treatment differs depending on whether the exporter purchased the goods new from a business or as second-hand from an individual.
However, opposing voices point out that the deemed input tax deduction itself should be considered a special tax privilege. Individual sellers do not pay VAT or issue tax invoices when selling second-hand goods. Therefore, if a certain amount is considered as input tax and deducted, the state is effectively granting a tax benefit on transactions where no actual tax was paid. Expanding the scope of deductions to general second-hand goods would require careful examination of which items and businesses should be eligible, and how to ensure equity with other industries.
In particular, photo cards, limited-edition goods, or luxury items, whose prices can skyrocket due to scarcity, could present further issues. If a deemed input tax deduction based on acquisition cost is applied to items where the second-hand resale price has risen significantly above the individual's original purchase price, it could lead to controversy as the price appreciation would also become subject to tax benefits.
Pushing to expand deductions for exports… Tax equity remains the challenge
The industry also cites the fact that transaction history is recorded on platforms as a basis for system improvement. Since 2023, the National Tax Service has been receiving transaction data from online second-hand platforms. Transactions on platforms like Danggeun, Bungaejangteo, and Joonggonara are also subject to data collection by tax authorities. Unlike the cash transactions between individuals in the past, the infrastructure to verify the parties involved and the transaction amounts is now in place.
In response, Representative Park Soo-young of the People Power Party introduced an amendment to the Restriction of Special Taxation Act this past April to allow deemed input tax deductions for second-hand goods with export declaration certificates. The intent is to include items whose actual export can be verified, rather than allowing deductions for all second-hand goods. The bill is currently under review by the National Assembly's Strategy and Finance Committee.
However, limiting deductions to exported second-hand goods may create another issue of tax equity. A situation could arise where a business buys the same second-hand item from the same individual but receives a deduction when selling to an overseas consumer, while failing to get one when selling to a domestic consumer. The challenge lies in balancing the policy goal of supporting the export industry with the need for tax equity between businesses selling domestically and those selling internationally.
In its recently published "2026 Parliamentary Audit Issue Analysis," the National Assembly Research Service identified the expansion of items eligible for deemed input tax deduction and the adjustment of deduction rates as items for the Ministry of Economy and Finance to review. The report suggests that, given the changes in the size and methods of the second-hand market, it is necessary to examine whether the existing eligibility and rates need adjustment.
An industry official stated, "Domestic second-hand items like K-pop photo cards and limited-edition goods are not just used items; they are products with scarcity and cultural value that are in high demand overseas. We must build an institutional foundation that allows us to nurture second-hand trade as a new export industry, rather than viewing it merely as person-to-person transactions."