

[BizHanKook] Although Hanwha Systems’ operating profit for the third quarter of this year increased by more than 60% compared to the previous year, its net profit plummeted by 97.5%. While its core businesses, such as the expansion of defense exports, grew, the decision to sell its stake in the U.S.-based Philly Shipyard resulted in losses from discontinued operations being reflected in its net profit.
What catches the eye is the transaction price of the Philly Shipyard stake. In late 2024, Hanwha Systems invested $60 million through its U.S. subsidiary, HS USA Holdings, to acquire a 60% stake in Philly Shipyard. Based on the exchange rate at the time of the public filing, this was approximately 91.8 billion KRW. Subsequently, in business combination accounting, the cash consideration transferred was recognized as approximately 88.2 billion KRW.
In September of this year, Hanwha Systems decided to transfer this stake to another U.S. entity within Hanwha Group for $237.6 million, which was approximately 325.1 billion KRW based on the exchange rate at the time of the announcement. In dollar terms alone, the transaction price for the stake has become about four times higher than the initial acquisition cost.
Philly Shipyard recorded a net loss of 126.9 billion KRW last year and was in a state of complete capital impairment, with total equity at -180 billion KRW. Despite this, the equity value was significantly marked up in this internal transaction.
However, it is difficult to conclude that Hanwha Systems reaped a massive investment profit just by comparing the initial $60 million investment with the current $237.6 million disposal price. After the acquisition, additional funds were injected into Philly Shipyard, and the shipyard’s deficits were also reflected in Hanwha Systems’ consolidated performance. Above all, this transaction is not a sale to an external investor but rather a restructuring of the governance structure to change the entity leading the U.S. shipbuilding business within Hanwha Group.
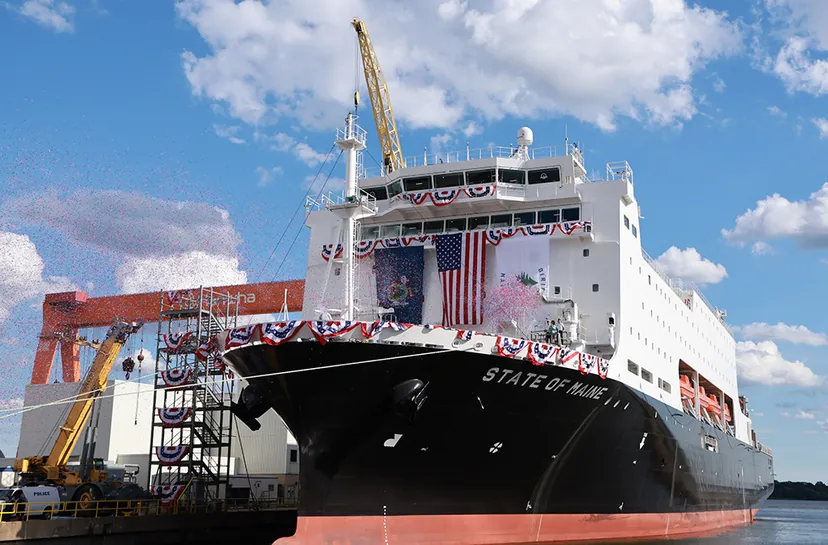
Operating Profit Up 60%, but Net Profit is 3.8 Billion KRW
On the 27th, Hanwha Systems announced that its consolidated revenue for the third quarter of this year was 831.598 billion KRW, with an operating profit of 99.15 billion KRW. These figures represent increases of 30.1% and 60.5%, respectively, compared to the same period last year. The operating profit exceeded the market forecast of 65.8 billion KRW by more than 50%.
Growth in the defense sector drove the results. Revenue increased in export projects, including the Cheongung-II Multifunction Radar (MFR) supplied to the UAE, Saudi Arabia, and Iraq, as well as domestic mass production projects such as the KF-21 AESA radar and avionics equipment. In the ICT sector, IT system construction projects for group affiliates also supported the performance. As of the end of the third quarter, the order backlog reached a total of 8.8653 trillion KRW, with 8.3956 trillion KRW from defense and 469.7 billion KRW from ICT.
However, the net profit shows the exact opposite. Net profit for the third quarter was 3.837 billion KRW, a 97.5% decrease from 150.495 billion KRW in the same period last year. On a cumulative basis from January to September of this year, the company recorded a net loss of 39.172 billion KRW, shifting into a deficit.
The cause is the U.S.-based Philly Shipyard. Hanwha Systems classified the business as a "discontinued operation" upon deciding to sell its stake in September. During the Q3 earnings conference call, the company explained that the decrease in net profit was due to the reflection of losses from the discontinued Philly Shipyard operations.
Losses from discontinued operations are reflected in net profit on an after-tax basis. Conversely, revenue and operating gains/losses related to Philly Shipyard are separated from the results of continuing operations. As a result, while Hanwha Systems’ operating profit increased significantly, its net profit appeared to drop sharply. Once the stake sale transaction is finalized, the related gains or losses, including the disposal gain/loss, will also be confirmed.
Stake Acquired for $60 Million, Internal Transaction Price $237.6 Million
Hanwha Group acquired Philly Shipyard in December 2024. At the time, Hanwha Systems invested $60 million through its U.S. subsidiary, HS USA Holdings, to secure a 60% stake. The amount based on the exchange rate at the time of the public announcement was approximately 91.8 billion KRW. Hanwha Ocean secured the remaining 40%.
During the process of finalizing the business combination accounting, the cash consideration transferred by Hanwha Systems in relation to the acquisition of the Philly Shipyard stake was recognized as approximately 88.16 billion KRW. Therefore, it is more accurate to view 88.2 billion KRW as the consideration for business combination accounting, while the actual investment amount at the time of the transaction was $60 million.
On September 18 of this year, Hanwha Systems decided to sell the entire 60% stake in Philly Shipyard held by HS USA Holdings to Hanwha Defense USA Shipbuilding LLC. The disposal price is $237.6 million, which is approximately 325.108 billion KRW based on the exchange rate at the time of the public notice. The transaction price was determined based on valuation by external professional institutions selected by the seller and the buyer. The scheduled disposal date is the 31st of this month.
Simply converting the transaction price of the 60% stake implies that the total value of Philly Shipyard was assessed at approximately $396 million. When Hanwha Group acquired the entirety of Philly Shipyard in 2024, the amount paid was approximately $100 million. In less than two years, the total equity value assessed in this internal transaction has become significantly higher than at that time.
However, this does not represent an investment profit for Hanwha Systems. After the acquisition, additional funds flowed into Philly Shipyard. Hanwha Systems’ public filings show that an additional stake acquisition transaction worth 88.7 billion KRW involving Philly Shipyard took place in 2025. This is why looking only at the initial $60 million investment and comparing it to this sale price does not properly reflect the actual funds invested.
Hanwha officials explain that since the recent acquisition of Philly Shipyard, a total of approximately $350 million has been invested in expanding facilities, human resources, and production capacity. However, since not all of this amount was directly borne by Hanwha Systems, it should not be equated with Hanwha Systems' individual investment amount. In addition, the operating losses and various operating expenses incurred by Philly Shipyard must also be taken into account.
Net Loss of 126.9 Billion KRW and Capital of -180 Billion KRW, Yet Valuation Increased
Looking only at the financial condition, it is not easy to explain the background behind the significantly increased value of Philly Shipyard. According to Hanwha Systems’ stake sale disclosure, Philly Shipyard recorded revenue of 570.633 billion KRW last year. The net loss reached 126.893 billion KRW. Total assets were approximately 519.9 billion KRW, and total liabilities were approximately 699.9 billion KRW. The total equity was approximately -180 billion KRW, indicating a state of complete capital impairment where liabilities exceed assets. In 2024, it recorded a net loss of approximately 207.2 billion KRW, and in 2023, approximately 85.2 billion KRW. In other words, it has been in a deficit for the past several years.
Nevertheless, in this internal transaction, the value of the 60% stake in Philly Shipyard was assessed at $237.6 million.
There is room to interpret that the strategic value as a production base to enter the U.S. naval ship market was reflected in the valuation, rather than its current financial performance.
Although Philly Shipyard has primarily focused on building merchant vessels in the U.S., Hanwha Group is transforming the shipyard into a “dual-use” shipyard that serves both the U.S. Navy and other federal agencies, as well as commercial customers.
Hanwha Defense USA and Philly Shipyard won their first project in March this year as subcontractors for Vard Marine US in the U.S. Navy’s Next Generation Logistics Ship (NGLS) program. While this is not a main contract for ship construction but a project involving market research, conceptual design, and design advancement, it is significant as it marks an entry into U.S. Navy business.
Hanwha Defense USA officially announced the acquisition of management rights for Philly Shipyard on the 27th, stating that it will foster the shipyard into a dual-use production base for the U.S. Navy, federal agencies, and commercial customers. As the possibility of entering the U.S. shipbuilding and defense market grows, it can be interpreted that the strategic value of a local production base capable of building both warships and merchant ships was valued higher than the currently loss-making financial statements.
However, it is difficult to conclude that this transaction price represents a verified enterprise value of Philly Shipyard in the external market. The buyer, Hanwha Defense USA Shipbuilding, is an entity in which Hanwha Defense USA and Hanwha Futureproof participate. Hanwha Defense USA is a U.S. defense subsidiary of Hanwha Aerospace. Ultimately, this is a transaction where the stake in Philly Shipyard held by Hanwha Systems is being moved to another U.S. entity within Hanwha Group, not bought by an external investor. The 40% stake in Philly Shipyard held by Hanwha Ocean will be maintained as is.
U.S. Shipbuilding Business Reorganized Around Hanwha Aerospace
The significance of this transaction is more clearly revealed in the reorganization of roles in Hanwha Group’s U.S. business rather than just a simple capital gain from the sale. Hanwha Defense USA Shipbuilding, which is acquiring the Philly Shipyard stake, involves Hanwha Defense USA and Hanwha Futureproof, the North American investment platform for Hanwha Group. Hanwha Defense USA is a U.S. defense entity controlled by Hanwha Aerospace.
Once the transaction is completed, management control of Philly Shipyard will pass from Hanwha Systems to Hanwha Defense USA. Hanwha Defense USA plans to oversee local shipbuilding operations directly while pursuing both naval and merchant ship projects.
Conversely, Hanwha Systems will be able to focus on its core businesses, such as defense electronics, space, and satellites, by excluding the loss-making shipyard from its consolidated scope. Hanwha Systems’ defense sector order backlog for the third quarter reached 8.3956 trillion KRW. With its existing defense electronics business, such as the Cheongung-II MFR and KF-21 AESA radar, growing, the necessity to hold a U.S. shipyard directly as a consolidated subsidiary has decreased compared to before.
Ultimately, the 97.5% decrease in Hanwha Systems’ third-quarter net profit is more influenced by the losses from discontinued operations that occurred during the process of changing the "owner" of its U.S. shipbuilding business rather than a slump in its core business. Despite Philly Shipyard being in a state of deficit and capital impairment, it was valued at a higher price than at the time of the initial acquisition based on the potential to enter the U.S. warship market and its strategic value as a local production base.
However, it is difficult to interpret that Hanwha Systems reaped massive investment profits by comparing only the initial $60 million investment and this disposal price. This is because additional funds were injected after the acquisition, the shipyard’s deficits were reflected in consolidated performance, and above all, this transaction is an internal group stake restructuring rather than an external sale.
If this transaction is finalized as scheduled on the 31st, the final gains/losses resulting from the exclusion of Philly Shipyard from consolidation and the stake disposal will be reflected in subsequent Hanwha Systems financial statements. Whether the increased valuation leads to an actual expansion of U.S. Navy-related business and improvements in Philly Shipyard’s performance will be a key variable in gauging future enterprise value.